How to Repatriate Rental Income and Sale Proceeds from Dubai to India: A Complete NRI Guide
2026-09-22
How to Repatriate Rental Income and Sale Proceeds from Dubai to India: A Complete NRI Guide
Owning property in Dubai is the easy part. Getting the rental income, or eventually the sale proceeds, back to India cleanly is where most NRI owners start second-guessing themselves. Search around, and you'll find guides warning about a USD 1 million cap, tax certificates, and RBI paperwork, most of which describes money leaving India, not money coming into it. If you're wondering how to send money from Dubai to India without triggering rules that don't even apply to your situation, this is the clarification you need before you make your first transfer.
Here's how the money actually moves, what tax you owe (often none), and which account it should land in.
The Direction That Matters: Which Account This Money Belongs In
Before methods or fees, get one thing straight: rental income and sale proceeds earned in Dubai are foreign income. That money should be credited to your NRE (Non-Resident External) account in India, not your NRO (Non-Resident Ordinary) account. The two exist for entirely different purposes, and mixing them up is the single most common mistake NRI property owners make.
Feature
NRE Account
NRO Account
What funds it
Foreign earnings from outside India
Income earned within India (rent, dividends, pension)
Interest tax
Tax-exempt
Taxable at 30% plus surcharge
Repatriation
Unlimited, no cap
Capped at USD 1 million per financial year
Paperwork to move funds
None required
Form 15CA and Form 15CB required
Your Dubai rental income and any proceeds from selling your Dubai unit go into the NRE account. Deposit them into an NRO account instead, and you've just subjected genuinely foreign money to India's NRO repatriation limit and paperwork, restrictions it was never meant to carry.
How to Send Money from Dubai to India: The Transfer Methods
Once you know where it's going, the "how" comes down to comparing cost against speed. There are five common channels:
Method
Rate vs Mid-Market
Typical Fees
Speed
UAE bank wire transfer
1 to 2% below
AED 25 to 100
1 to 3 days
Exchange houses (Al Ansari, Lulu, Al Fardan)
0.5 to 1% below
AED 5 to 20
Same day to 1 day
Digital remittance apps (Wise, Remitly)
Near mid-market
0.3 to 0.9% flat
1 to 2 business days
Indian bank UAE branches (SBI, HDFC, ICICI, Axis)
Competitive
Low for existing customers
Often same day
Direct NRE account funding
Varies by bank
Varies
1 to 3 days
For smaller, regular rental transfers, exchange houses or a digital app usually beat a bank wire on total cost once you add up the rate margin and the flat fee. For a large one-off transfer, like sale proceeds from a property, it's worth calling around, since exchange houses and Indian bank UAE branches will often negotiate better rates on bigger amounts than their advertised rate card suggests. There's no cap on how much an NRI can remit into India for personal funds; the only documentation hurdle is UAE anti-money-laundering checks on unusually large transfers, which your bank or exchange house will flag and ask you to explain with source-of-funds documents.
NRI Rental Income Tax: Do You Actually Owe Anything in India?
This is where most of the anxiety turns out to be unnecessary. Your Indian tax liability depends entirely on your residential status under Section 6 of the Income Tax Act, not on where your property happens to be.
Non-Resident (NR): you don't meet the residency thresholds (broadly, fewer than 182 days in India during the year), and only your India-sourced income is taxable. Your Dubai rental income and any Dubai property sale proceeds fall outside Indian tax entirely.
Resident but Not Ordinarily Resident (RNOR): applies if you've been a non-resident in 7 of the previous 10 years. Your Dubai income stays exempt unless it comes from a business or profession actually run from India.
Resident and Ordinarily Resident (ROR): if you've spent enough time in India to cross the residency thresholds, your global income, Dubai rental income included, becomes fully taxable in India under Section 5(1).
Since the UAE charges no personal income tax, the India-UAE Double Taxation Avoidance Agreement doesn't offer much relief if you do end up in ROR status; there's no foreign tax paid to credit against your Indian liability, so the income gets taxed at your normal Indian slab rate. The practical takeaway: as long as you keep genuine NR or RNOR status, your Dubai rental income can sit entirely outside the Indian tax net. It's your day count in India each year, not the property's location, that decides this.
Selling Your Dubai Property: What Happens to the Proceeds
Selling an Indian property as an NRI triggers TDS, capital gains filings, and often a Form 15CA/15CB process before you see your own money. Selling a Dubai property doesn't work the same way, and it's worth knowing that upfront so you don't apply the wrong checklist.
Because the property, and therefore the gain, sits entirely outside India, an NR or RNOR owner has no Indian capital gains event to report on that sale. There's no Indian TDS to deduct, because no Indian buyer or Indian registrar is involved in the transaction at all. The proceeds simply move from your UAE bank account to your NRE account in India through any of the transfer methods above, the same way your rental income does. The only tax question that matters is the one from the section above: is your residential status NR or RNOR at the time, or have you drifted into ROR?
NRO Account Repatriation: When It Actually Applies to You
If your Dubai-earned money goes into an NRE account, none of this section applies to you, and that's worth repeating because a lot of generic NRI finance content bundles it in regardless. NRO account repatriation, and the rules around it, only come into play if you're moving money that was earned inside India: rent from a property you still own in India, dividends from Indian investments, or proceeds from selling an Indian asset.
If that describes part of your situation, here's what the Reserve Bank of India's framework requires for NRO repatriation:
The cap: up to USD 1 million per financial year (April to March), an aggregate limit covering all NRO remittances combined, not per transaction
Form 15CA: a declaration you file yourself on the Income Tax e-filing portal before the transfer
Form 15CB: a certificate from a practicing Chartered Accountant confirming applicable taxes have been paid, and the remittance is compliant, required for amounts over Rs 5 lakh, which covers most property-related transfers
Timeline: two to four weeks with complete documentation in hand, longer if paperwork is incomplete or a CA needs to chase down TDS records
The two systems, NRE for foreign income and NRO for Indian income, are meant to stay separate. If you've been depositing Dubai rental income into an NRO account out of habit or bank default settings, it's worth asking your bank to correct that going forward. Money that never needed the USD 1 million cap or the CA certificate shouldn't be carrying that weight.
Getting Your Remittances Right From Day One
Set this up correctly before your first rental payment lands, not after months of transfers have gone into the wrong account. Confirm your Indian bank has your Dubai income routing to an NRE account, keep basic source-of-funds records (lease agreements, sale contracts) in case a transfer gets flagged for AML review, and revisit your residency status calculation every financial year, since a longer stay in India than usual can shift you from NR into ROR without you realizing it.
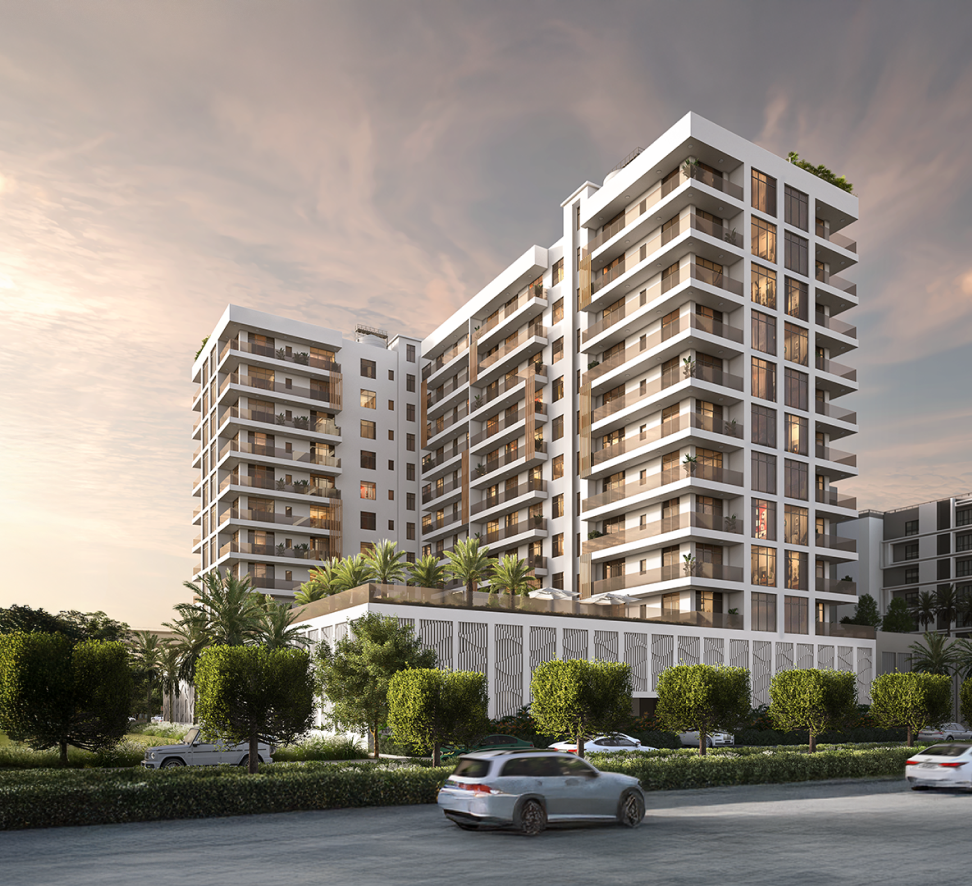
If you're still deciding which Dubai property fits your investment plans, both rental yield and eventual resale matter for how smoothly this process goes. A compact rental-focused unit likeTriana Residences in Jumeirah Garden City suits owners planning on steady rental remittances, while a larger family property likePurvanchal Villa in Jebel Ali Hills is more of a long-term hold. Browse the Purvanchal projects to compare what's currently available, and if you already own and want help thinking through your specific remittance setup,get in touch directly rather than guessing at rules that may not even apply to you.
Frequently Asked Questions
1. How do I send money from Dubai to India as an NRI?
Transfer it through a bank wire, exchange house, or digital remittance app into your NRE account in India. Since it's foreign income, there's no cap and no extra paperwork required.
2. Is NRI rental income from a Dubai property taxable in India?
Not if you hold Non-Resident or RNOR status; only India-sourced income is taxed for you. It only becomes taxable if you cross the residency thresholds and become a Resident and Ordinarily Resident.
3. Does the USD 1 million NRO repatriation limit apply to my Dubai rental income?
No. That limit and its Form 15CA/15CB requirement apply only to money earned inside India and held in an NRO account. Foreign income routed to an NRE account has no such cap.
4. Do I pay Indian capital gains tax when I sell my Dubai property?
Generally no, as long as you're an NR or RNOR, since the property and the gain sit entirely outside India. There's no Indian buyer, TDS, or registrar involved in a Dubai property sale.
5. What's the cheapest way to transfer money from Dubai to India?
For smaller, regular transfers, exchange houses and digital apps usually cost less than a bank wire once fees and rate margins are added up. For larger one-off transfers, it's worth comparing rates directly with your bank or exchange house first.